For owners with a handful of employees
You're the CEO, the bookkeeper, and the HR department. Let's take one of those off your plate.
Fifteen minutes with Adam, a licensed agent. Every plan you qualify for, side by side, in writing. If he can't beat what you have, he'll say so.
- 97 five-star Google reviews
- No cost, no obligation
- Licensed in 16 states
Too small for a group plan. Too successful for a subsidy.
Three to five people, a lease, payroll every other Friday, and a year that finally made real money. Then you went to Healthcare.gov for yourself and the subsidy came back as zero. The group-plan quote from the big carriers wanted a headcount you don't have.
So you're paying too much for your own coverage and your best employee is asking about benefits you can't offer. That's how you lose good people to a company with an HR department.
What nobody told you: there's a private market of coverage built for exactly this size of business. It doesn't show up on the Marketplace, and it works for an owner's household and a small crew without a group contract.
Someone should have shown you that a long time ago. That's what the Coverage Check is for.
How the Coverage Check works
Three steps. No homework. Nothing to download.
 1
Tell us the basics
One minute on the form. Where the business is, who's in your household, and roughly what you made last year. Mention the team on the call and Adam will price that too.
 2
Take the 15-minute call
Adam shares his screen and walks you through every option side by side, Marketplace plans included. Real numbers, plain English, no pressure. Ask anything.
 3
Decide with the facts in front of you
If there's a better fit, Adam handles the paperwork. If your current plan wins, he'll tell you that too. Either way, you finally know.
Why people in your line of work call Adam
He writes coverage for owners and their people.
Adam works with small teams every week. He shares his screen, shows you what coverage looks like for you and your household first, then what it looks like if you bring your people in. Every option side by side, including the Marketplace. If you're better off where you are, he'll say so.
Book My 15-Minute Coverage CheckWhat people say after the call
Real Google reviews, quoted word for word. Five stars across 97 of them.
- ★★★★★
I had a great and easy experience working with Adam. Very professional and informative, he helped make the process of registering for insurance easy. I definitely recommend anyone looking for private insurance to go with Adam W.
- ★★★★★
Adam was fast and thorough. He answered all my questions and customized my coverage to what I needed and kept it in a price range I could afford!
- ★★★★★
Adam is fantastic! He walked us through every option in detail and made the whole process easy to understand. Thanks to his guidance, we found the best plan for our family without any stress.
Who you'll actually talk to
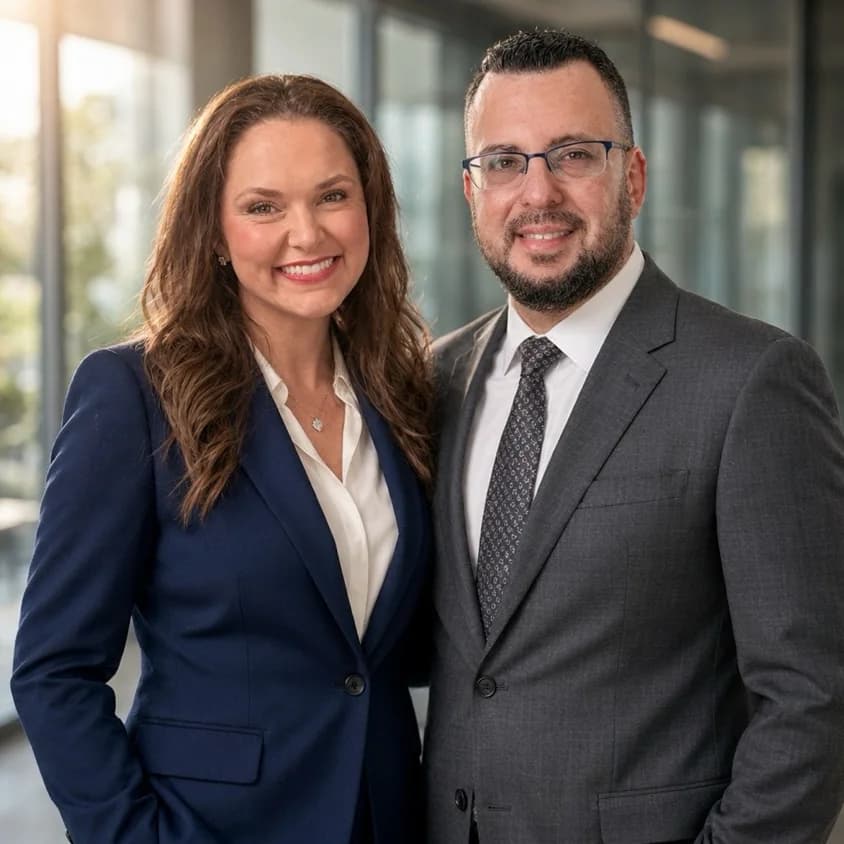
A husband and wife who know the system. Not a call center.
Adam and Crystal Winter run Next Level Health & Life from Oviedo, Florida. Adam works the private market, the plans built for self-employed people and families who make too much for a subsidy. Crystal specializes in the Marketplace and short-term options, so if a subsidy is the smarter move for you, Adam loops her in and she takes it from there.
Between the two of them, every situation gets an honest answer. Licensed in 16 states. Reachable at (954) 806-9897. And when you call back with a question next March, you get the same two people.
What if you do qualify for a subsidy?
Then you'll hear it from Adam on the call, not find out later. When the numbers say the Marketplace is your best deal, he'll say so, then put you and Crystal in a group text so she can get you enrolled there. Same team, same honest answer. You won't get talked into a private plan that costs you more. That's the whole point of the check.
The questions people ask before they book
How many employees do I need for this to work?
For private-market coverage, you don't need a minimum. Adam writes it for owners alone and for small crews. Tell him how many people you have and he'll show you what fits.
Do I have to cover my employees to cover myself?
No. Start with your own household. If you want to add the team later, Adam will show you how.
Can I pay for part of my employees' coverage?
Many owners do. How you set that up is a question for your accountant. Adam will give you the real cost so you can decide what to offer.
Is this actually free?
Yes. The Coverage Check costs nothing and you don't owe us anything afterward. Like every licensed agent, we're paid by the insurance carrier if you enroll in a plan, and that never changes your premium. Adam works with a specific private-market carrier and Crystal covers the Marketplace and other options, so between them you see the real choices.
What is a "private-market" plan?
Health coverage sold outside the government Marketplace. These plans aren't eligible for subsidies, which is why Healthcare.gov doesn't list them. For households above the subsidy line, they're often a better fit on price, network, or both. Adam will tell you which applies to you.
Do I have to wait for Open Enrollment?
Not for most private-market plans. Many can start the first of next month. Marketplace plans follow the Open Enrollment calendar unless you have a qualifying life event, and Crystal can walk you through that.
Will you ask about my health?
Not on this form. We only ask for what we need to pull the right plans: where you live, household size, and a rough income range. Anything a specific carrier requires later, Adam explains on the call before you share it.
What happens after I submit?
You get a text right away confirming we received it. Then Adam calls from (954) 806-9897, usually within minutes during business hours. If you miss it, he'll text to find a better time. No robo-dialers, no call center.
I already have a plan. Is this still worth it?
That's the best time to do it. Adam compares your current plan line by line against what's available. If yours wins, he says so and you keep it with peace of mind. If it doesn't, you'll see exactly why.
Fifteen minutes.
Fifteen minutes. Then you have a real number for yourself, your family, and your people, and one less job on the owner's desk.
Open Enrollment runs November 1 to January 15. Coverage that starts January 1 has to be locked in by December 15. Fifteen minutes now beats a rushed decision in December.